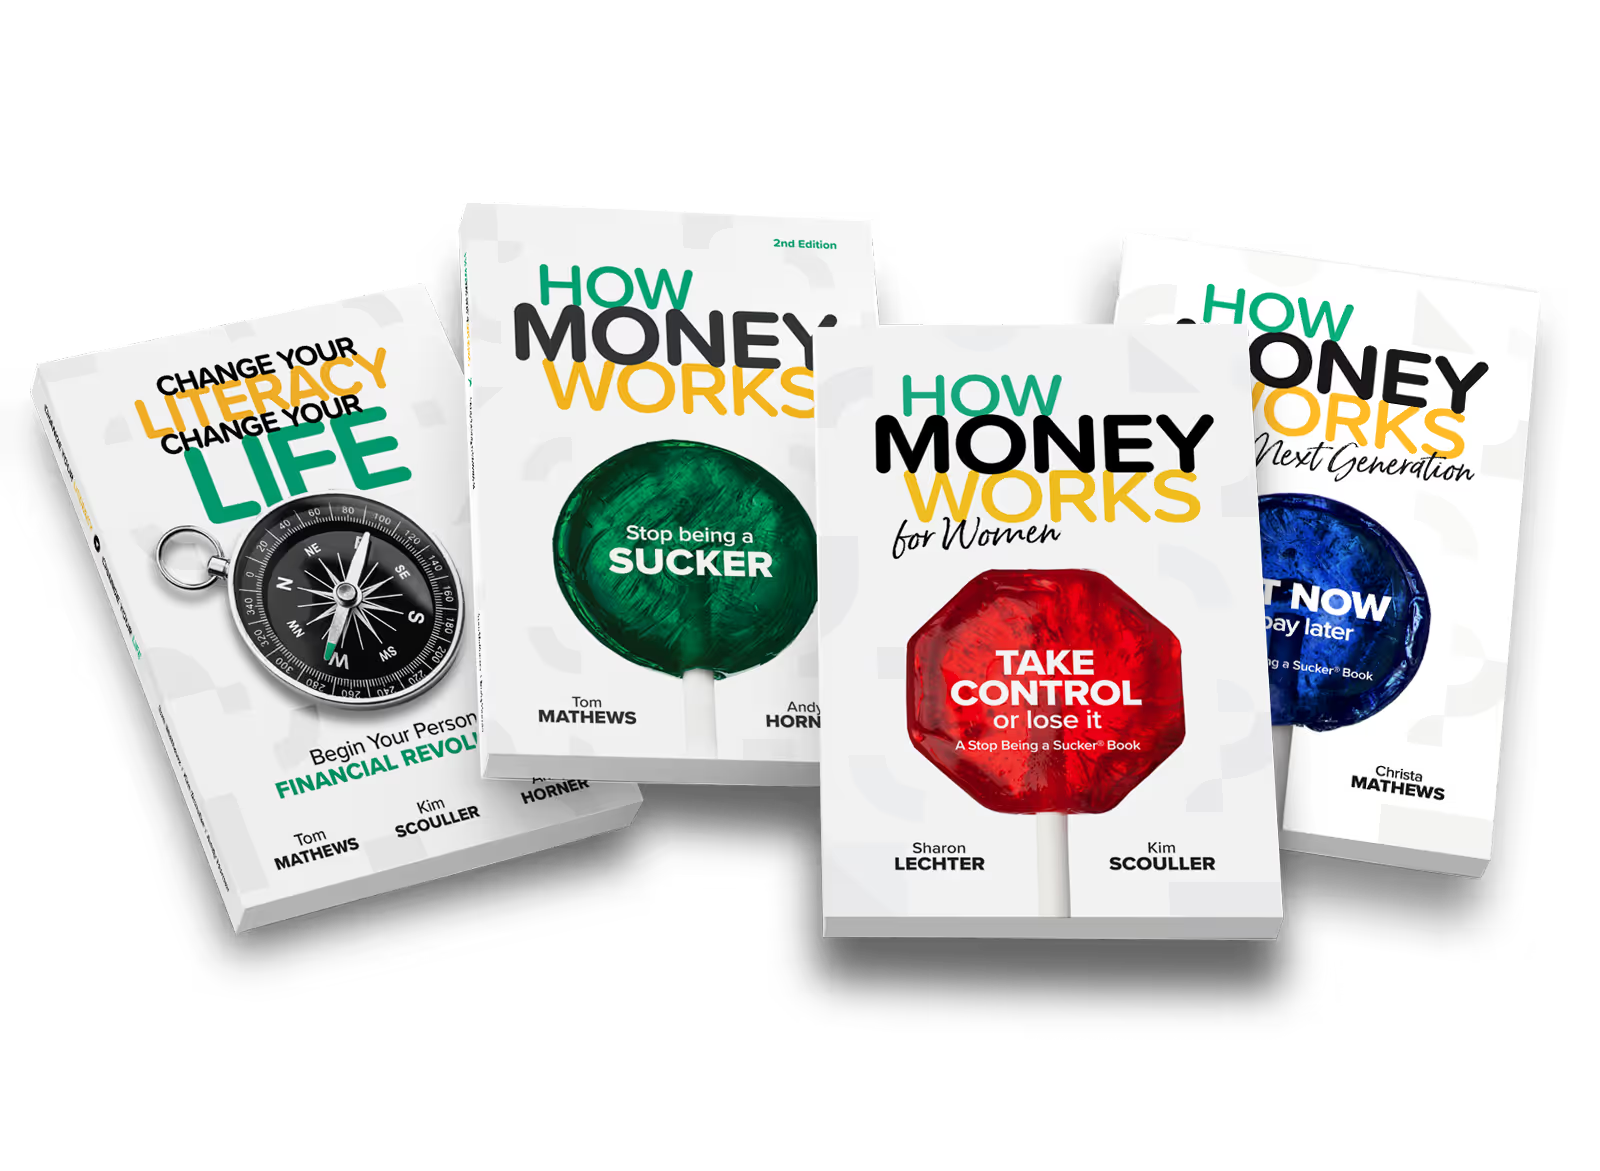
 Request a copy of our book(s)
Long Term Care: A Family Conversation Guide
5 Questions to Ask Before It’s Too Late
When it comes to money, everyone has blind spots. One of the biggest? Long-term care. Not because it’s complicated—though it can be—but because it requires something most people avoid: talking about the future, aging, and what happens when someone we love can’t fully care for themselves.
It's no wonder only 17% of people have even started planning for long-term care. That means most families are unprepared for the moment when decisions need to be made. And when the moment comes, it’s usually under stress, at a hospital, with emotions high and time short.
We believe in teaching people how money works—before they need it. Part of that is learning how to have “that talk” with the people you love most. So today, we’re breaking that silence with five clear questions every family should ask now—before it’s too late.
These questions won’t just help you create a plan. They’ll help you protect relationships, preserve dignity, and prepare emotionally and financially for what may be one of life’s most significant transitions.
But let’s start with the truth...
The Conversation Nobody Wants, But Everybody Needs
It’s hard to picture life when someone who once raised us, supported us, or stood beside us suddenly needs our help just to get through the basics: eating, bathing, moving, remembering.
It’s even harder to imagine what that might mean for our own family, savings, relationships, job—and future.
That’s why this conversation needs to happen way before life forces it. The sooner we have it, the more options, clarity, and peace we gain. That’s how we replace crisis with confidence.
So grab a notebook or open a shared doc. Pass around the coffee, not the awkward silence. And let’s walk through the five questions that can change everything.
Question 1: What Type of Care Would You Prefer, and Where?
Before dollars, policies, or logistics—start with dignity. What kind of life does your loved one want if they can’t live exactly the way they do now?
Ask:
- Do you want to stay at home as long as possible?
- If you needed daily help, would you prefer a professional caregiver or family?
- Would you ever consider assisted living or a memory care facility? Why or why not?
Each option has pros and cons.
- Home care offers familiarity and comfort, but it may require major upgrades—or a rotating team of caregivers.
- Assisted living provides structure and social interaction, but it can be expensive and emotionally challenging.
- Nursing care or skilled care is there when medical support is necessary, but it’s often a last resort.
This question grounds your planning in values, not money. It helps your loved one feel seen and respected. And it empowers you to make decisions with them—not for them—if the time comes.
Question 2: How Will We Pay for It?
This is where money steps in as a tool, not a tension. The average cost of long-term care in America is rising each year. As of 2024, the numbers look like this:
- Home health aide (full-time): ~$68,000/year
- Assisted living facility: ~$54,000/year
- Private room in nursing home: ~$108,000/year
And remember: 20% of people age 65+ will need care for longer than five years.
So how do you prepare? By breaking down the options:
1. Savings and Assets – Retirement accounts, pensions, IRAs, property sales.
2. Insurance – Long-term care insurance or hybrid life/long-term care policies.
3. Government Programs – Medicaid (needs qualification), VA benefits, limited Medicare support.
4. Family Contributions – Often the least discussed and most stressful option unless planned ahead of time.
Talk openly. Ask:
- Do you already have long-term care insurance or a policy with a care rider?
- Are you counting on using home equity or savings?
- What income sources will be available in retirement?
This isn’t about prying—it’s about clarity. The biggest financial disasters come from silence, not shortfalls.
Question 3: What Documents Do We Need—and Where Are They?
Every financial educator has seen it: families scrambling through drawers, folders, and email accounts trying to find a power of attorney or trust document after a crisis hits.
Avoid that chaos.
Create a list of essential documents and make sure they’re updated and accessible:
🗂️ Legal Documents
- Power of Attorney (financial)
- Power of Attorney (healthcare / medical proxy)
- Living will / advance directive
- Last will and testament
- Trust documents (if any)
- POLST (Physician Orders for Life-Sustaining Treatment)
💳 Financial & Insurance Records
- Bank and retirement account details
- Long-term care insurance policies
- Life insurance policies
- Deed or mortgage statements
- Pre-paid funeral or burial plans
🔑 Where They’re Stored
- Physical copies: folder, safe, binder, lockbox
- Digital copies: encrypted folder, cloud storage, shared drive
- Password access: write it down or use a password manager
This isn’t paperwork. It’s protection. It’s your emergency instruction manual.
Question 4: Who Will Be Responsible for What?
One of the most painful moments in caregiving is when the weight falls on one person simply because they’re the closest, most available, or most emotionally involved.
That’s why a smart family assigns roles—not burdens.
Have an honest, practical conversation:
- Who lives closest? Who’s willing and able to help in-person?
- Who can manage finances, bills, and insurance?
- Who can provide emotional support or stay in touch with doctors?
- Who will be the medical decision-maker if needed?
Assigning roles now prevents resentment later. And it helps each person operate out of strength—not obligation.
You may even decide to form a "care team"—a shared system of regular check-ins and responsibilities. No family should handle long-term care alone. But no one should be surprised by it, either.
Question 5: What’s Most Important to You—Even If Circumstances Change?
This is the most powerful question because it goes deeper than logistics.
It’s not just “Where do you want to live?” It’s:
- What makes life worth living for you?
- What would you want to keep doing, no matter what?
- What would you not want us to do, even if we think it’s “best”?
This is where you discover the core:
"I want fresh air every day."
"I don’t want to live where I can’t see my grandkids."
"Don’t put me on machines if I’m not coming back."
"I’m okay downsizing—but I want my books, my garden, and my music."
These things matter. And when emotions rise or medical staff start asking hard questions, these answers give you a compass.
This is how you honor someone long after they’re able to explain themselves.
Bringing It All Together: Start the Conversation This Week
You don’t need to have every answer today, but you do need to ask the questions. Silence is the enemy of preparedness.
And here’s the surprising truth:
Most people are relieved when someone starts the conversation. They’ve often been thinking about it, worrying about it, or avoiding it quietly. You’re not bringing up something new—you’re bringing it into the light.
Your Action Plan
✅ Step 1: Schedule the Talk
Choose a calm day, a familiar place, and give everyone a heads-up.
✅ Step 2: Use the 5 Questions
Print them, write them, speak them—but stick to them.
✅ Step 3: Listen First
Don’t correct or judge—just capture everything.
✅ Step 4: Follow Up
Make a checklist: documents to gather, roles to assign, funding gaps to explore.
✅ Step 5: Bring in a Pro
This is the point where you should speak with a qualified financial professional—someone who can provide policy reviews, cost projections, benefit breakdowns, and planning strategies tailored to your situation.
Because the worst thing we can do is wait.
Before You Go: One Simple Truth
Planning for long-term care isn’t morbid. It’s loving. It says: “I don’t want my pain or vulnerability to become your crisis or confusion.”
It’s an act of stewardship, strength, and clarity.
This is how we protect families. This is how we preserve relationships under pressure. This is how we change the financial culture—one conversation at a time.
And the best part?
Now that you know what to do, you can help others do it too.
Let’s start the talk. Let’s protect the people we love. Let’s teach it forward.
Money Monsters: 7 Habits That Eat Your Budget Alive

How to Spot, and Stop, the Financial Creatures Hiding in Plain Sight
They lurk quietly.
In your bank app.
In your Amazon cart.
In that “small” subscription you forgot to cancel six months ago.
They’re the Money Monsters, habits that seem harmless day-to-day but quietly feast on your financial future.
Most people don’t lose control of their money because of one big mistake. It’s usually a series of small leaks: automatic withdrawals, thoughtless swipes, emotional splurges—that nibble at every paycheck until your budget looks like Swiss cheese.
The good news? You can trap these monsters once you learn to recognize their footprints.
Let’s shine a flashlight on the seven most common ones.
1. The Subscription Slime
It starts innocent enough:
“Only $9.99 a month.”
Then there’s another. And another.
Music, streaming, fitness, cloud storage, photo editing, meditation, pet food delivery, and the “free trial” you forgot to end. One by one, they blend into your bank statement until you’ve built a small financial ecosystem feeding on your income.
According to studies, the average person underestimates their monthly subscriptions by more than 70%. What you think is $40 often ends up being $110 or more.
How to fight it:
- Audit quarterly. List every recurring charge and ask, “Would I sign up for this today?”
- Cancel before you decide. If you miss it after a week, resubscribe. Most people never do.
- Bundle intentionally. Some services offer shared plans—just make sure you’re splitting costs fairly.
Subscriptions aren’t the enemy. Forgetting about them is.
2. The Latte Leech
We’re not here to shame coffee drinkers. This monster isn’t about caffeine—it’s about autopilot.
A daily $6 stop for coffee feels tiny. Yet over a year, that adds up to $1,500–$2,000. If you’re also grabbing lunch out three times a week, you could be draining another $2,500 annually.
That’s a plane ticket, an emergency fund, or two months of retirement contributions disappearing into foam and convenience.
How to fight it:
- Track one “small” habit for a month. You’ll likely gasp.
- Choose your ritual days (Fridays only, for example).
- Redirect the savings automatically. Brew at home → transfer $6 to savings. Small moves compound.
Your coffee isn’t evil—but unexamined habits are.
3. The Debt Goblin
This creature feeds on one emotion: avoidance.
You stop checking balances because they stress you out. You make minimum payments hoping it’ll all sort itself out later. Meanwhile, interest multiplies quietly in the dark.
A $5,000 credit card balance at 22% interest—making only minimum payments—can take 20 years to pay off and cost nearly $11,000 in total. That’s the Debt Goblin’s favorite meal: your future freedom.
How to fight it:
- Face the numbers. Write every debt, balance, interest rate, and payment.
- Choose your weapon:
- Snowball: Pay smallest balance first to gain momentum.
- Avalanche: Pay highest interest first to save money long-term.
- Call your creditors. Ask about hardship programs or rate reductions—you’ll be surprised how often they help.
The Debt Goblin thrives on silence. Once you face it, it loses power.
4. The Lifestyle Werewolf
This one hides under the full moon of success. You get a raise, and suddenly your spending rises with it. New clothes. Nicer dinners. A “deserved” upgrade.
It’s not greed—it’s human nature. Psychologists call it hedonic adaptation: our baseline for “enough” keeps shifting upward.
Here’s the problem: when lifestyle rises as fast as income, wealth never grows. You’re working harder, earning more, and still feeling behind.
How to fight it:
- Lock in your savings rate. If your income jumps 10%, increase savings or investing by 5%.
- Delay upgrades 90 days. If you still want it after the wait, it’s likely a genuine improvement, not a dopamine hit.
- Define “enough.” Write down what a good life actually looks like for you. Otherwise, you’ll keep chasing someone else’s version.
You can’t out-earn the Lifestyle Werewolf—you can only outsmart it.
5. The Impulse Imp
This sneaky creature loves checkout screens and “limited time” banners. It thrives on emotion: boredom, stress, or celebration.
It’s not just the big splurges—studies show most people make three unplanned purchases per week. Those micro-decisions, often under $50, add up to thousands annually.
How to fight it:
- Use the 24-hour rule. Want something? Screenshot it. Wait a day. Most desires fade with time.
- Shop from a list only. Whether online or in-store, anchor your actions to a plan.
- Block the bait. Unsubscribe from marketing emails and turn off push notifications.
Impulse buying isn’t about weakness—it’s about environment. Control that, and you control the Imp.
6. The Budget Phantom
This one is tricky because it looks responsible. You tell yourself you have a budget—maybe even a spreadsheet somewhere—but you never actually track spending in real time.
That’s how the Budget Phantom wins: by hiding reality behind rough guesses.
A Gallup poll once found that only 32% of households have an active, written budget. The rest are flying blind—and shocked when their card declines.
How to fight it:
- Automate your awareness. Use free tools that categorize spending automatically.
- Budget by buckets. Keep it simple: Needs (50%), Wants (30%), Future (20%).
- Schedule a weekly 10-minute check-in. Look at one number: “How much left in each category?”
Budgets aren’t about restriction. They’re about permission—to spend confidently within limits you’ve chosen.
7. The Comparison Kraken
No monster drains happiness faster.
You see a friend’s trip to Italy or a neighbor’s new SUV and think, “I’m behind.” Suddenly, your perfectly fine life feels inadequate.
Comparison fuels overspending. You justify upgrades not because you need them, but because you want to feel equal. That emotion—envy dressed as motivation—is expensive.
How to fight it:
- Recognize social media for what it is: highlights, not reality.
- Unfollow triggers. Protect your peace like you protect your wallet.
- Track your progress, not theirs. A personal net-worth chart or savings goal tracker makes your own wins visible.
Financial confidence doesn’t come from status—it comes from direction. If you’re moving forward, you’re doing better than you think.
The Monster-Proof Plan
Spotting the creatures is step one. Caging them takes consistent, simple actions—no silver bullets required.
- Name your top three monsters. Which habits feel most familiar? Awareness beats shame.
- Attack one at a time. Small, focused wins stick longer than total overhauls.
- Create automatic systems. Auto-transfers to savings, auto-debt payments, auto-investing. Automation is garlic for financial vampires.
- Use accountability. A financial educator, friend, or partner keeps you honest and encouraged.
- Replace, don’t remove. Cut the bad habit, but fill the gap—brew coffee with friends, plan a “no-spend Saturday,” or turn budgeting into a challenge game.
You can’t just eliminate habits; you must rewrite them.
The Transformation: From Fear to Freedom
In TheMoneyBooks, we often say financial literacy isn’t about perfection—it’s about direction. Once you start learning how money really works, the monsters shrink fast.
Think about what each of these habits costs—not just in dollars, but in stress and missed opportunities:
- The Subscription Slime steals awareness.
- The Latte Leech steals momentum.
- The Debt Goblin steals freedom.
- The Lifestyle Werewolf steals contentment.
- The Impulse Imp steals purpose.
- The Budget Phantom steals clarity.
- The Comparison Kraken steals joy.
Add those up, and you see why so many families feel stuck no matter how much they earn. But add up the opposite traits—awareness, momentum, freedom, contentment, purpose, clarity, joy—and you get wealth, in every sense.
A Final Word
There’s a reason our mission begins with education. Once you understand how these monsters operate, you can’t unsee them—and that’s a good thing. Awareness is permanent protection.
This week, choose one. Just one.
Shine a light on it.
Measure its cost.
Make one small change.
Maybe that’s canceling an unused subscription. Maybe it’s deleting a shopping app. Maybe it’s opening your first investment account instead of another store card.
Whatever it is, it’s a step toward your Best Friday, your Debt-Free December, your Financially Free Future.
When you win one battle, momentum builds. When you win all seven, your money finally works for you—and not the monsters.
Ready to see where you stand?
Take the Financial Literacy Quiz and find out which habits are hiding in your financial life. Then get one of our TheMoneyBooks and connect with a financial educator to arm yourself with the knowledge to keep every dollar working toward your goals.
Because the only thing scarier than Money Monsters…
is pretending they’re not there.
Why Every Family Needs a Plan
Estate Planning: A Simple Guide for Every Family
Estate planning isn’t just for the wealthy or the retired. It is a basic life plan that organizes what you own and what you want so your family can act with clarity during tough moments. Think of it as future-proofing your wishes, your kids’ care, and your medical decisions.
Below is a general, plain-English guide to help you and your family get started.
A quick reminder this is not legal advice. If you want help personalizing any of this, speak with a qualified financial professional who can coordinate with your legal and tax advisors.
What Estate Planning Really Covers
At its core, an estate plan answers three big questions:
- Who gets what? You decide how your assets should be distributed.
- Who cares for your children? You can legally name guardians for minors.
- Who speaks for you in a medical crisis? You can record your health care wishes and appoint decision-makers if you cannot decide for yourself.
With a plan, you keep control over these decisions. Without one, state rules and the court process have a larger say.
Why So Many Families Plan Around Probate
Probate is the court-supervised process for paying debts and distributing assets after someone dies. It can take time, add costs, and make details public, which is why many people try to avoid it when they can.
A revocable living trust is often used to help assets pass outside probate when it is properly set up and funded. This can make distribution faster and more private for your beneficiaries.
General guidance: A financial professional can help you understand whether probate is likely for your situation, and how titling, beneficiary designations, and trusts could change the outcome for your family.
If You Have Children, Start Here
Guardian designations are one of the most important parts of a plan for parents of minors. If you do not name guardians, a court may need to decide who steps in. Naming primary and backup guardians puts you in charge of that decision and reduces uncertainty for your kids.
Helpful idea: Write a short “parenting letter” that shares values, routines, and preferences. Store it with your documents so guardians understand the heart behind your instructions.
The Health Care Side Most People Forget
Estate planning also covers your medical voice:
- Health care surrogate or proxy: The trusted person who can make treatment decisions if you cannot.
- Living will or advance directive: Your preferences for life support and end-of-life care.
- HIPAA authorization: Permission for your chosen people to access medical information so care is not delayed.
Clear documents spare your family from guesswork during emergencies.
The “Starter Toolkit” Most Households Use
A comprehensive, trust-based set of documents typically includes:
- Revocable Living Trust
- Last Will & Testament
- Financial Power of Attorney
- Health Care Surrogate/Medical POA
- Living Will/Advance Directive
- HIPAA Authorization
- Personal Property Memorandum
- Assignment of Personal Property
- Pet Trust (if you have animals that need care)
General guidance: A financial professional can help you coordinate these documents with how your accounts and policies are titled, so the paperwork and the real-world assets match.
Common Mistakes To Avoid
1) Waiting “until later.” Emergencies do not check your calendar. Begin with simple steps you can finish this week.
2) Creating a trust but not funding it. A trust only works for assets that are titled to it or directed to it through beneficiary designations. Ask for a funding checklist and go account by account. (Your legal documents and your account records should tell the same story.)
3) Skipping guardians. Name primary and backup guardians for minor children and let them know you have chosen them.
4) Forgetting medical directives. Financial instructions are only half the plan. Add your health care surrogate, living will, and HIPAA authorization.
5) Hiding documents. Store originals safely. Share copies or secure digital access with the people who will need them.
6) Never reviewing. Revisit your plan after major life changes such as marriage, divorce, the birth or adoption of a child, a move to a new state, or starting a business. A periodic review helps keep your plan aligned with your life.
A 7-Day “Action” Plan
Use this week to get traction. Tackle one step each day and you will be further along than most households.
Day 1 — Inventory
List your accounts, real estate, insurance, business interests, and debts. Note titling and beneficiaries.
Day 2 — People
Choose a successor trustee, financial and medical agents, and guardians. Confirm they are willing. Pick backups.
Day 3 — Health
Complete your health care surrogate, living will, and HIPAA authorization. Share copies with your agents.
Day 4 — Build
Create your revocable living trust and will. Keep your instructions clear and values-driven.
Day 5 — Fund
Retitle assets where appropriate and update beneficiary designations. Use an assignment of personal property and a personal property memorandum for household items and keepsakes.
Day 6 — Guardian pack
Write your parenting letter. Add school, medical, and routine details. Tell guardians where documents are kept.
Day 7 — Share and store
Give key people copies or secure digital access. Store originals safely. Put a reminder on your calendar to review in 12 months.
General guidance: If your week is packed, ask a financial professional to help you batch these steps into one or two working sessions.
Will vs. Trust: A Simple Way to Think About It
A will is valuable for naming guardians and directing distributions, but it usually needs probate before assets move. A revocable living trust, when properly funded, is commonly used to streamline transfers and increase privacy for your family. Many people use both: a will that coordinates with a trust.
Your situation may differ based on your state, the types of accounts you hold, and your goals for timing and privacy. This is where a conversation with a financial professional pays off.
Keep It Practical
- Start simple. Do the next right step, not everything at once.
- Match paperwork to accounts. Titles and beneficiaries should reflect your written wishes.
- Make it findable. Your plan should be easy for loved ones to locate and follow.
- Review as life changes. Update after major events or at regular intervals.
A Gentle Nudge To Act
Estate planning is a kindness to your future self and to the people you love. It turns anxiety into order, and public court processes into private family transitions. This week, pick one step and complete it. Then keep going.
If you want help translating this guide into a plan that fits your life, contact a qualified financial professional. They can coordinate your plan across documents, account titling, beneficiary choices, insurance, and storage, and bring in legal and tax experts where needed. That support can save time, reduce stress, and help your plan work the way you intend.
The financial nightmare of domestic violence

October is Domestic Violence Awareness Month. Many people think of bruises or broken bones, but there’s another weapon of abuse that leaves scars you can’t see on the outside: financial abuse.
Experts estimate that more than 10 million adults experience domestic violence, and almost 100% also experience financial abuse. Sadly, we rarely talk about it because its effects aren’t always visible, but it is just as devastating.
Economic abuse usually takes the form of control, sabotage or exploitation. Abusers may drain bank accounts, hide assets, deny or limit access to money, demand a detailed accounting of every dollar spent or criticize financial decisions until the victim doubts herself. It can also mean threatening to withhold money, forcing the victim to miss or be late to work, belittling her accomplishments or even physically preventing her from going to work or school. Abusers will also run up debt in their victim’s name, ruining her credit score and leaving her with little to no access to financial resources.
The end result is the same: dependency. When you don’t have money of your own, when your credit is destroyed and when you’ve lost jobs because of abuse, you’re trapped. The financial chains can feel as strong as physical ones.
The costs ripple far beyond individual households. Consider these staggering facts:
• Research shows that survivors of intimate partner violence lose 8 million days of paid work every year.
• More than half of survivors lose a job due to abuse, and about 70% report being blocked from working at all.
• Nearly 60% of victims suffer harm to their credit by their abuser.
• The overall workplace productivity costs are $1.3 trillion.
These aren’t just personal tragedies. They’re economic crises. Every lost job, every ruined credit score, every foreclosure or eviction caused by abuse strains our communities, our workplaces and our economy. Employers lose talent, banks absorb defaults, and taxpayers foot the bill for social services and health care.
Why aren’t we more outraged? Why don’t we talk about financial abuse in the same breath as physical violence? Because it’s quieter. But it’s no less destructive.
Ending financial abuse has to become a priority if we’re serious about ending domestic violence. That means recognizing the warning signs both for potential victims and for those of us who can help. It also means systemic change.
Employers must understand that domestic violence is a workplace issue. Flexibility, support and resources can mean the difference between a survivor keeping or losing her job. Financial institutions should be trained to recognize red flags and provide confidential support for clients in crisis. Lawmakers should strengthen protections so survivors aren’t punished for debts forced on them by abusers, and so leaving doesn’t mean financial ruin. Starting over is difficult enough; starting behind seems an almost impossible hurdle.
Most important, we need to keep naming financial abuse for what it is: violence. Control over money is control over life itself. Stripping someone of their ability to earn, save or plan isn’t just bad behavior. It’s a calculated act to keep them powerless.
If October is a month of awareness, let’s be truly aware. Domestic violence doesn’t always show up as bruises. Sometimes it shows up as an empty bank account, a destroyed credit report or a career cut short. Until we end financial abuse, we will never fully end domestic violence.
If you’re a business leader, look at how your company can support employees who may be silently struggling. If you’re in finance, consider what policies or safeguards your institution could put in place. And if you’re a friend or family member, know the signs and know that asking, “Why doesn’t she just leave?” is the wrong question. The right question is, “How can we help her find the resources to rebuild her life and financial foundation?”
Economic independence leads to freedom. And freedom is what every survivor of domestic violence deserves.
— Kim Scouller
As published on triblive.com. https://triblive.com/opinion/kim-scouller-the-financial-nightmare-of-domestic-violence/
The Workplace Life Insurance Illusion

Why It’s Not Enough
When most people start a new job, they scan through the benefits package, sign a few forms, and feel reassured when they see life insurance listed as part of the deal. It feels like a built-in safety net — a box checked with no effort and no cost.
But here’s the uncomfortable truth: for most families, that workplace policy isn’t nearly enough.
According to the 2025 Facts About Life Insurance – Workplace Benefits report, the median basic coverage employers provide is either a flat $20,000 or just 1x salary. For a household that depends on two incomes, a mortgage, and future goals like college tuition or retirement, that number doesn’t stretch very far.
Yet more than half of workers (57%) believe their employer’s coverage is enough. That false sense of security is what we call the workplace life insurance illusion.
Why We Rely Too Much on Workplace Coverage
On the surface, workplace coverage seems convenient:
- You don’t have to shop around.
- You don’t have to fill out medical forms or go through underwriting.
- You don’t have to pay extra premiums (basic coverage is often free).
It’s a benefit that feels simple and automatic — and in a busy world, simplicity is attractive.
But simplicity can also be deceiving. That $20,000 payout might sound like a lot in the abstract, but when stacked against real expenses, it doesn’t go far. For many families, it wouldn’t cover even six months of mortgage payments, child care, or daily living costs.
Almost half of households (49%) that rely only on workplace life insurance admit their family would face financial hardship in less than six months if a wage earner died unexpectedly. That’s not long-term protection — that’s a ticking clock.
The Awareness Gap
Here’s the kicker: many workers don’t even realize what they have.
- 36% of U.S. workers are not fully aware they even have coverage through their employer.
- Only 29% of adults with workplace-only coverage say they’re very or extremely knowledgeable about life insurance.
This knowledge gap leaves families exposed in two ways:
- They overestimate the protection they have.
- They underestimate what they really need.
In TheMoneyBooks we teach: If it matters, measure it. Your financial future, your family’s security, and your legacy matter — which means you can’t leave them unmeasured, uncalculated, or unprotected.
What “Enough” Really Means
So how much life insurance do families actually need?
Experts typically recommend coverage equal to 10–15 times your annual income. That’s enough to cover:
- Final expenses (funeral/burial costs average $8,000–$12,000).
- Mortgage payoff or ongoing housing costs.
- Replacing lost income so surviving family members can maintain their lifestyle.
- Childcare, college tuition, or eldercare.
- Retirement savings support for a spouse.
When you compare that with $20,000 or 1x salary, it’s easy to see the gap. If you earn $60,000 a year, a workplace policy of $60,000 is just one year’s income — hardly enough to secure the next decade, let alone a lifetime.
Generational Realities
The illusion plays out differently across generations:
- Gen Z and Millennials often rely heavily on employer benefits, with 23–26% saying workplace life insurance meets their needs. They’re young, just starting their financial journeys, and may assume work coverage is enough “for now.”
- Gen X is most reliant, with 37% saying they depend completely or mostly on workplace life insurance. At the very stage when financial responsibilities are heaviest, they’re leaning on policies that don’t cover nearly enough.
- Baby Boomers are less reliant, but many are underinsured heading into retirement.
Across the board, reliance on employer coverage is a fragile strategy. Jobs change, employers downsize, and benefits shift. Your family’s protection shouldn’t depend on the HR department’s decisions.
The Hidden Risks of Workplace-Only Coverage
- It ends when your job ends.
If you leave your job — voluntarily or not — your coverage often disappears. That means if you switch careers, retire early, or get laid off, you may suddenly be uninsured. - It doesn’t grow with your needs.
Life events like marriage, children, or buying a home increase the amount of protection you need. Employer policies rarely adjust in proportion. - It may not be portable.
Some plans offer the option to convert workplace coverage into an individual policy, but the premiums can be much higher than if you had purchased coverage independently earlier in life. - It can create false peace of mind.
Believing you’re covered when you’re not leads to dangerous inaction. By the time many people realize the shortfall, health issues or age have made new coverage more expensive or unavailable.
Measuring Your Real Needs
The antidote to the workplace illusion is clarity. You don’t have to guess whether your employer’s coverage is enough. You can measure.
Ask yourself:
- How much would my family need to replace my income for 10–15 years?
- Do I want my mortgage paid off if something happens to me?
- Do I want to fund college education for my children?
- Do I want to leave money behind to care for aging parents or build a legacy?
Run those numbers through a simple life insurance needs calculator. (TheMoneyBooks offers one, as do most financial educators.) The gap between your needs and your employer’s policy will quickly become obvious.
The Role of Education
Education changes everything. Workers who understand how life insurance works, what it costs, and what it covers make better decisions.
Right now, myths dominate the conversation:
- “It’s too expensive.” (In reality, many young, healthy adults can get $500,000 of term coverage for less than $1 a day.)
- “I don’t need it until I have kids.” (By then, premiums may be higher, and health conditions may complicate approval.)
- “Work provides enough.” (The numbers prove otherwise.)
In the 2025 Barometer Study, only 29% of consumers overall believe they’re knowledgeable about life insurance. Education is the first step in closing that gap.
A Real-World Example
Imagine this scenario:
Jessica, a 38-year-old marketing professional, earns $80,000 a year. She has two kids, ages 6 and 9. Her employer provides life insurance equal to her salary — $80,000.
If Jessica passed away unexpectedly, her family’s expenses would not disappear. Her mortgage alone is $1,700 a month. Add in food, childcare, healthcare, and everyday bills, and her family spends nearly $5,000 a month.
Her employer’s life insurance payout would last them about 16 months — just over a year of survival. But what about the next 10 years of raising kids? What about college? What about her spouse’s retirement plan?
Jessica realizes she actually needs closer to $800,000–$1 million in coverage. Her employer’s policy covers just 10% of that need.
That’s the workplace life insurance illusion in action.
How to Protect Beyond Work
The good news: the solution is straightforward.
- Calculate your real need. Don’t guess. Use a calculator or work with a financial professional.
- Get your own policy. Term life insurance is affordable and flexible. Owning your own policy ensures protection follows you, not your job.
- Supplement, don’t replace. View workplace coverage as a supplement — a helpful add-on, not your only strategy.
- Review regularly. Needs change as life changes. Review coverage after major milestones like marriage, buying a home, or having children.
Why This Matters
Life insurance isn’t about numbers on a policy statement. It’s about the day your family faces the unthinkable. Will they have the resources to grieve without financial chaos? Will your children stay in the same home and schools? Will your spouse keep the retirement plan intact?
The illusion of workplace coverage is dangerous because it whispers, “You’re fine.” But fine isn’t enough.
In TheMoneyBooks, we repeat a principle that applies here: protect first, then grow. Growth without protection is like building a house without a foundation. One storm can wipe it out.
It's Time to Stop Being a Sucker®
The statistics are clear:
- Median workplace coverage = $20,000 or 1x salary.
- 57% of employees believe that’s enough.
- 49% of families relying on workplace coverage admit they’d struggle financially within six months of a wage earner’s death.
Those numbers add up to a nationwide illusion. The solution? Education, measurement, and taking control.
Your employer’s policy is a start, but it’s not the finish line. Protect your family with coverage that truly matches your needs — because if it matters, measure it.
Why Women Can’t Afford to Wait on Life Insurance

When it comes to financial security, women in America are standing on a fault line. For years, surveys have shown that women lag behind men in life insurance ownership. The latest 2025 Insurance Barometer Study confirms it: fewer than half of women (48%) say they have life insurance, compared with 54% of men.
That may sound like a small gap, but when you zoom in on the reality behind those numbers, it’s startling. Millions of women are one unexpected life event away from leaving their families exposed to debt, financial hardship, and broken dreams.
And here’s the most important part: it doesn’t have to be this way.
In our TheMoneyBooks series, we teach a core principle: protect first, then grow. Financial literacy is the bridge between worry and confidence, and nowhere is that more urgent than in the conversation about life insurance.
The Ownership Gap: More Than a Number
So why do fewer women own life insurance?
The data gives us a roadmap:
- Knowledge gap: Less than a quarter (23%) of women feel very knowledgeable about life insurance, and more than 1 in 10 say they know nothing at all.
- Cost misperception: Three-quarters of women overestimate the cost by 3–5 times the actual amount. Most admit they’re just guessing.
- Decision delay: Many say they haven’t “gotten around to it,” or that other financial priorities keep pushing it down the list.
- Complexity of underwriting: Over half (55%) say they don’t understand the process at all.
The result? A financial blind spot that affects not only women but their families, communities, and long-term wealth-building potential.
The Stakes Are Higher for Women
This gap isn’t just about percentages — it’s about lives. Women consistently report higher financial concerns than men:
- 42% worry about having enough for a comfortable retirement.
- 40% worry about saving for emergencies.
- 37% worry about long-term care needs.
- 35% worry about supporting themselves if illness or injury prevents them from working.
These are not small anxieties. They’re the real-life scenarios that derail families financially. Without protection in place, these risks become crises.
Nearly half of women (49%) believe their families would experience financial hardship within six months if the primary wage earner died unexpectedly. Three in ten say hardship would hit within just one month.
That’s not “someday” risk — that’s right now.
The Myths That Hold Women Back
Let’s confront three of the most damaging myths that keep women from getting covered.
Myth 1: “Life insurance is too expensive.”
In reality, a healthy 30-year-old woman can buy a 20-year, $500,000 term policy for the price of a daily latte. Yet, because of misinformation, most women believe it costs three to five times more than it really does.
Education flips this myth on its head. Once women see real quotes, the affordability becomes clear.
Myth 2: “I don’t have dependents, so I don’t need it.”
Life insurance isn’t just about children. It’s about anyone who relies on your income — a partner, aging parents, or even yourself if you want coverage for final expenses, debt payoff, long-term care options, or legacy giving. Waiting until you “need it” usually means paying more later or facing health-related challenges that limit your options.
Myth 3: “I’ll get around to it eventually.”
Time is not your friend here. The younger and healthier you are, the more affordable coverage is. Procrastination raises costs — and sometimes closes the window entirely if illness strikes before you’ve secured coverage.
Women’s Financial Power: Why Insurance Is Essential
Here’s the bigger picture: women are not just participants in the financial system. They’re becoming its leaders.
- Women control more than $10 trillion in U.S. financial assets, a number expected to triple in the next decade.
- Women make the majority of household purchasing decisions and are increasingly the breadwinners.
- Women are at the center of the Great Wealth Transfer, which will see trillions move across generations in the coming years.
With so much financial power, leaving the foundational step of protection undone undermines the very progress women have fought for. Life insurance isn’t a “nice-to-have.” It’s a critical part of building lasting wealth.
The Role of Financial Literacy
At TheMoneyBooks, we’ve seen firsthand how financial literacy changes this conversation. Once women understand:
- How life insurance works,
- Why it’s affordable, and
- How it protects their long-term goals,
the decision becomes easier.
Knowledge doesn’t just close the gender gap — it closes the confidence gap.
When women are informed, they move from being unsure and hesitant to decisive and empowered. That shift has ripple effects across their families and communities.
Shopping Smart: How Women Prefer to Buy
The study also highlights how women want to shop for coverage:
- 40% would research online but ultimately buy through an agent or financial professional.
- 26% would complete the purchase entirely online.
- 27% are actively looking for direction from a financial professional.
That tells us something important: women don’t just want products. They want guidance. They want someone who educates, listens, and helps them align protection with their goals.
This is where our mission fits perfectly. TheMoneyBooks series doesn’t sell policies — they build understanding. Once that foundation is laid, working with a financial professional becomes a natural next step, not a pressured sales pitch.
Stories That Inspire Action
Sometimes numbers aren’t enough. Stories bring the message home.
Consider the woman who thought life insurance would cost her hundreds of dollars a month. When she saw the actual quote — less than her family’s streaming bill — she cried with relief.
Or the mom who bought coverage after realizing her children would face financial hardship within weeks if anything happened to her. That single decision gave her peace of mind she hadn’t felt in years.
Or the single professional who purchased coverage to lock in affordable rates now, knowing she wants to start a family in the future. She called it “a gift to my future self.”
These aren’t isolated stories. They’re everyday women who realized waiting was the real risk.
The Urgency of Now
Here’s the truth: every month without coverage is a gamble. The longer you wait, the higher the cost, the fewer the options, and the greater the risk of being unprotected when your family needs it most.
Financial literacy gives women the power to:
- See the real cost — and recognize affordability.
- Understand the purpose — protecting loved ones, securing goals, building legacy.
- Take timely action — because tomorrow is never guaranteed.
This isn’t fear-based. It’s reality-based. Women who act now build a wall of protection that gives them the freedom to focus on growth, opportunity, and long-term wealth.
How TheMoneyBooks Can Help
HowMoneyWorks for Women: Take Control or Lose It was created for exactly this reason. It addresses the unique challenges women face, from longer lifespans to pay gaps to caregiving responsibilities. It offers practical, approachable education — not jargon, not intimidation.
The book doesn’t just tell women what to do. It shows them how to think differently, how to ask the right questions, and how to spot the myths that keep too many stuck.
When paired with a conversation with a trusted financial educator, it becomes a game-changer. It’s the difference between feeling exposed and feeling protected.
A Call to Action
The numbers from the 2025 Barometer Study are clear: women’s reported need for life insurance is high, but ownership lags behind. Millions are exposed. Millions are waiting.
But waiting is costly.
The path forward is simple:
- Get educated.
- See real numbers.
- Protect your family.
- Then focus on building wealth.
Life insurance isn’t the end of the story. It’s the foundation of the story you want to write.
Final Word
If you’re a woman reading this, the question isn’t “Do I need life insurance?” The question is “Can my family afford for me not to have it?”
The answer, for nearly everyone, is no.
Don’t wait. Start today. Your family — and your future self — will thank you.
From Financial Stress to Financial Freedom

The Weight You Can’t See
You feel it before you name it. That tightness in your chest when the credit card bill arrives. The restless nights wondering if your savings will last through retirement. The nervous glance at gas prices, grocery receipts, or your 401(k) balance when the market dips.
Financial stress doesn’t just live on spreadsheets. It shows up in our health, our relationships, and even the choices we make day to day. According to the 2025 Schroders US Retirement Survey, 65% of Americans say they worry about money too much — and more than half believe that financial stress is harming their health.
But here’s the truth: financial stress isn’t permanent. It’s a signal. And with the right plan, you can move from uncertainty to clarity, from constant worry to confidence — from financial stress to financial freedom.
Why Financial Stress Feels So Heavy
Money stress is unique because it’s both practical and emotional.
- It’s practical because you need money to meet life’s basics: housing, food, transportation, healthcare, and the occasional cup of coffee that makes the morning a little better.
- It’s emotional because money represents security, opportunity, and even identity. When it feels scarce or uncertain, it can make the future feel unpredictable — or worse, hopeless.
In the survey, 81% of retirement plan participants said they were at least slightly concerned about outliving their money. And 53% feared losing too much in a market downturn. These aren’t abstract worries — they’re rooted in a real gap between where people are and where they feel they need to be.
The average worker believes they’ll need $1.28 million to retire comfortably. Yet nearly half expect to have less than $500,000 — and one in four expect less than $250,000.
That gap is where stress lives.
Stress Has a Cost You Can Measure
Financial stress doesn’t just keep you up at night — it can cost you in ways you don’t always see.
- Lost Opportunities – When you’re stressed, you tend to make defensive, short-term decisions instead of proactive, long-term moves. That means missed investments, delayed savings, or avoiding beneficial risks like starting a side business.
- Higher Debt – The survey found that 25% of workers have borrowed from their retirement plan to pay down credit cards. It’s a cycle that delays your future security.
- Health Impact – Chronic stress can lead to high blood pressure, weakened immunity, and burnout. Money stress can become health stress, which becomes even more money stress.
If you’re feeling it now, you’re not alone. But you don’t have to stay here.
The Path to Financial Freedom
Financial freedom isn’t just about having a certain number in the bank — it’s about being in control of your money, instead of your money controlling you.
In TheMoneyBooks series, we call this process The 7 Money Milestones — a clear, step-by-step plan that anyone can follow, no matter where they’re starting from. Let’s walk through them as the antidote to financial stress.
1. Secure Your Financial Education
The first milestone isn’t saving money — it’s understanding money. Without a solid foundation, even a high income can disappear quickly.
- Learn how debt works (and how interest really adds up).
- Understand the difference between assets that grow and expenses that drain.
- Get familiar with financial terms so you can make decisions with confidence.
📌 Action Step: Take the Financial Literacy Quiz to find out where you stand today. It’s only 25 questions, and it’s the fastest way to see your blind spots and start closing them.
2. Protect Your Income & Loved Ones
You can’t build wealth if you’re always one crisis away from losing it. This is where proper insurance — especially life insurance — comes in.
Too many people put off this step, thinking they’ll “get to it later.” But coverage is cheaper when you’re younger and healthier, and it’s the only way to make sure your family’s future isn’t left to chance.
3. Build an Emergency Fund
A major cause of financial stress is the constant “What if?” What if the car breaks down? What if you lose your job? What if you have a medical emergency?
Without a safety net, these events become financial earthquakes. With one, they’re just bumps in the road.
📌 Action Step: Aim for 3–6 months of expenses in a separate, easily accessible savings account.
4. Manage Debt the Right Way
Not all debt is created equal, but all debt should be managed with intention. High-interest debt — especially credit cards — is the biggest stress amplifier.
Consider the avalanche method (paying off the highest interest first) or the snowball method (paying the smallest balances first for quick wins).
The key is to have a plan and stick to it. Every balance you pay off is a piece of stress you remove from your life.
5. Save & Invest for the Future
Once your foundation is in place, it’s time to grow your money.
Your retirement plan — 401(k), 403(b), or IRA — is more than an account; it’s your future lifestyle in the making. Yet the survey found 59% of workers wish they had more guidance on how to invest.
📌 Action Step: Review your allocation. Too many people default to “whatever’s easiest,” which often means sitting in too much cash (23% of participants are doing just that). That’s a silent killer for your long-term growth.
6. Increase Your Income Over Time
You can only cut expenses so far — at some point, growth comes from earning more. That could mean advancing in your career, starting a side business, or building passive income streams.
The difference between someone who barely meets retirement needs and someone who exceeds them often comes down to consistent, intentional income growth over decades.
7. Protect & Build Your Legacy
The ultimate level of financial freedom is knowing that your success won’t stop with you. That means proper estate planning, charitable giving if it’s part of your vision, and ensuring the next generation starts from a stronger place.
Turning the Corner on Stress
The shift from financial stress to freedom doesn’t happen overnight. But here’s what you’ll notice once you start:
- You’ll sleep better, because you have a plan.
- You’ll make decisions with confidence, because they’re based on knowledge, not fear.
- You’ll start to see possibilities instead of roadblocks.
Financial stress thrives in uncertainty. Freedom thrives in clarity.
Your Next Step Starts Here
The biggest mistake you can make is waiting until “things settle down” to start fixing your finances. Life rarely gets less busy or less expensive on its own.
Start now:
- Take the Financial Literacy Quiz to know exactly where you stand.
- Connect with a financial educator to see what you need help with.
- Read one of our TheMoneyBooks to master the 7 Money Milestones in depth.
Your future self will thank you.
Because financial freedom isn’t just for the wealthy — it’s for anyone willing to take the steps to get there.
The Great American Money Illusion

Why Knowing What “Bad” Really Means Can Change Everything About Your Financial Future
Right now, the average savings account in the U.S. earns just 0.45% interest. Everyone agrees—that’s not great. But do you really understand how bad it is?
Let’s break it down.
Americans have over $11 trillion sitting in traditional savings accounts, earning barely anything. That’s $11 trillion of hard-earned money, just sitting there—waiting, not working. It feels safe, sure. But it’s not helping people build wealth or even keep up with rising costs. In fact, that money may be quietly losing value over time thanks to inflation.
Meanwhile, banks aren’t letting it sit. They take those deposits and lend them out at 10, 15, even 20% interest—making huge profits in the process. They win. You don’t. That’s the real money illusion.
Maybe it’s time to ask a better question: What should your money be doing for you?
What Does 0.45% Actually Mean?
It may seem like a small number, but the reality is staggering. At 0.45%, your money takes about 160 years to double.
That’s not a typo.
Using something called the Rule of 72 (just divide 72 by your interest rate), you can estimate how long it takes your money to double. At 0.45%, most of us won’t see our savings double in our lifetime—or even in our children’s lifetime.
Now look at the other side: Credit card interest rates average over 20%. That means the money you save grows glacially, while the money you borrow doubles every few years.
It’s not just unfair. It’s devastating.
The $1 Trillion Trap
As of mid-2025, credit card debt in America passed the $1 trillion mark. With interest rates averaging 20%, here’s what that really means:
- Your $10,000 savings at 0.45%? It earns less than $500 over a decade.
- That same $10,000, loaned out by a bank at 20%? It grows to over $60,000 in 10 years.
One sits. One soars. The difference is what you know—and how you act on it.
This is the cost of not understanding how money works. It’s the cost of doing what feels normal, instead of what’s actually smart. It’s the difference between building wealth... and watching others build it with your money.
Why Do So Many Still Use Low-Yield Savings Accounts?
It’s not because people are careless. It’s because we’ve been taught to think “safe” means “smart.”
Let’s look at why most people still park their money in these accounts:
- Safety: FDIC insurance protects deposits up to $250,000. That gives people peace of mind.
- Habit: For generations, we’ve been told that saving in a bank is the right way to manage money.
- Convenience: It’s easy. Your money is accessible. No penalties, no delays.
But there’s a hidden cost: Every year, inflation quietly erodes your money’s purchasing power. You lose value—and don’t even realize it.
How Did We Get Here?
After the 2008 financial crisis, interest rates were cut to stimulate the economy—and they stayed low for over a decade. Even now, with recent rate hikes, the average savings account still offers just 0.45%.
Meanwhile, banks continue to profit—charging double-digit interest on everything from mortgages to car loans to credit cards. Your money earns pennies. Theirs earns billions.
The gap between what you earn and what they earn isn’t just wide—it’s growing.
What If You Saw Money Differently?
At TheMoneyBooks, we believe the biggest problem in personal finance isn’t lack of income—it’s lack of understanding.
That’s the illusion.
Millions of Americans are stuck in financial survival mode, not because they’re lazy or irresponsible, but because they’ve never been taught how money really works. They’re playing a game without knowing the rules.
Now imagine what happens when people do learn the rules.
- They stop relying on luck and start using strategy.
- They stop settling for scraps and start building something real.
- They stop being at the mercy of the system and start flipping the script.
It’s not about being perfect. It’s about being informed.
Linear vs. Exponential Thinking
Most middle-class Americans think about money in linear terms: Work hard, save a little, repeat.
But the wealthy? They think exponentially. They understand leverage, compound growth, and how to make money work for them—not the other way around.
This mindset shift doesn’t start with money. It starts with education. That’s where TheMoneyBooks comes in.
We’re here to make these ideas simple, accessible, and actionable for everyone.
So, What Can You Do?
Knowledge is power—but only if you use it. If you’re ready to break free from the money illusion, here’s how to start:
✅ Test your financial literacy at TakeTheFLQ.com. This fast, free quiz shows where you stand—and where to grow.
✅ Read one of TheMoneyBooks. These short, powerful books make personal finance simple, relevant, and practical—no jargon, no fluff.
✅ Talk about it. Share what you learn with friends and family. Change spreads when people start having better conversations about money.
Albert Einstein once said:
“Compound interest is the eighth wonder of the world. He who understands it, earns it. He who doesn’t, pays it.”
That’s not just a quote. That’s your call to action.
If you’ve ever felt like money is working against you, now’s your chance to flip the script. Take back control. Learn how money really works. And help build a future that actually works for you.
Because the truth is, your financial future isn’t just something that happens to you. It’s something you choose.
No Buy July

What We Learned and Why You Should Try It
If you’ve been scrolling through social media this month, chances are you’ve seen people talking about No Buy July. Maybe it was a friend sharing their weekly savings, a TikTok about resisting impulse buys, or an Instagram post celebrating a month of mindful spending.
No Buy July has been everywhere—and for good reason. It’s a simple, powerful challenge: spend only on the essentials for 31 days and hit pause on everything else. No takeout. No impulse Amazon orders. No “just because” shopping trips.
Now that July is wrapping up, it’s the perfect time to reflect on what this challenge was all about, what participants learned, and why it’s never too late to give it a try, even if you missed it this time around.
What Is No Buy July?
At its core, No Buy July is a 31-day spending freeze. The rules are simple: only spend on the essentials like groceries, bills, transportation, and health-related expenses. Everything else? On hold.
That means:
- No new clothes or shoes.
- No takeout or coffee runs.
- No random online shopping sprees.
- No “therapy-through-Target” moments.
It’s not about deprivation, it’s about awareness. It’s about taking a step back to see how much of your spending is driven by actual need versus habit, boredom, or stress. And for many, it’s been a game-changer.
What We Learned This Month
For those who joined the challenge, No Buy July wasn’t just about saving money, it was about gaining insight into their habits. Here are some of the biggest lessons participants shared:
1. Spending Is Often Emotional
Many people realized how often they shop to cope with stress, boredom, or even as a reward. No Buy July forced them to find healthier (and cheaper) ways to deal with those feelings, like journaling, exercising, or simply sitting with the discomfort.
2. Small Purchases Add Up
It’s not always the big-ticket items that drain your bank account. It’s the $5 coffee here, the $20 impulse buy there. By cutting out these “little” expenses, participants were shocked at how much they saved in just 31 days.
3. We Already Have Enough
From rediscovering forgotten items in their closets to getting creative with what they already owned, many people found that they didn’t need to buy more, they just needed to appreciate what they already had.
4. Saying “No” Feels Empowering
There’s something deeply satisfying about resisting the urge to spend. It’s not just about saving money, it’s about proving to yourself that you’re in control of your choices, not your impulses.
What If You Didn’t Join This Time?
If you didn’t participate in No Buy July, don’t worry, you’re not too late. The beauty of this challenge is that it’s not tied to the calendar. You can start your own spending freeze any time of year. Call it No Spend September, Mindful Money March, or just a personal reset—what matters is the intention behind it.
Here’s how to get started:
1. Set Your Rules
Decide what counts as an essential expense (groceries, bills, gas) and what doesn’t (takeout, clothes, subscriptions). Be honest with yourself about what you can realistically cut back on.
2. Pick a Timeframe
It doesn’t have to be a full month. Start with a week, two weeks, or whatever feels manageable. The goal is progress, not perfection.
3. Set a Goal
What will you do with the money you save? Whether it’s paying off debt, building an emergency fund, or saving for something special, having a clear goal will keep you motivated.
4. Find Substitutes for Spending
You’re not just cutting out spending, you’re replacing it with something better. Instead of:
- Shopping → Declutter your space
- Scrolling → Read a book or take a walk
- Impulse buying → Make a wishlist for later
Why It’s Worth Trying
No Buy July isn’t just about saving money—it’s about gaining clarity, confidence, and control. It’s about breaking free from the cycle of mindless spending and making choices that align with your values and goals.
Even if you only try it for a week, you’ll likely walk away with a new perspective on your habits, and a little extra cash in your pocket.
Ready to Start Your Own Challenge?
No Buy July is a mirror. It reflects our habits, our triggers, and our priorities. It pushes us to get honest about where our money’s really going, and where we’d rather it go.
We believe financial literacy isn’t just about numbers. It’s about decisions. The kind you make at a checkout line. Or in a text from a friend. Or while scrolling through sales.
This challenge isn’t about guilt. It’s about growth.
So whether you’re doing a full No Buy July, a Low Buy Summer, or just skipping Amazon this week—know this: every small shift counts.
Your future self will thank you.
The Psychology of Not Saving

Why Knowing Isn’t Enough
Most people know they should be saving more money. But most aren’t.
Sound familiar?
You’ve heard the advice. You’ve probably nodded along at a workshop or underlined a sentence in a book (hopefully one of ours). You’ve maybe even said to yourself, “This is the month I’ll finally get ahead.” Yet the bank account still looks lean, and the emergency fund? Not quite off the ground.
So what gives?
According to Vanguard’s 2025 Consumer Survey, 71% of Americans say they plan to shift their savings approach this summer—focusing more on emergency funds and flexibility.
That’s encouraging. But there's a problem: most people don’t actually follow through.
This is the knowledge-action gap. And it’s one of the biggest threats to your financial future.
Let’s explore what’s really holding people back—and what you can do to move forward.
The Willingness to Save Is There
The good news? People aren’t ignoring the importance of saving. In fact, 71% of those surveyed want to shift their financial behavior this summer to focus on more intentional saving.
But despite the motivation, many Americans struggle to act on it. When asked what’s standing in the way:
- 28% said they don’t have enough time
- 28% said they don’t have enough money
- 24% said they don’t know where to start
These aren’t signs of laziness or irresponsibility. They’re signs of overwhelm. People want to save, but they feel stuck, scattered, or just plain unsure.
Why Good Intentions Aren’t Enough
At TheMoneyBooks, we’ve seen this over and over again: most people don’t need more information—they need more clarity, coaching, and next steps.
Let’s look at the three most common barriers.
1. “I don’t have time.”
Between work, family, and constant distractions, many people feel like there’s no space left for managing money. But often, “I don’t have time” is just another way of saying, “I don’t know where to start.”
Building a savings habit doesn’t require hours a week. It might take just 15 minutes to open a dedicated account or automate a deposit. The issue isn’t time—it’s priority.
When saving becomes part of your system instead of another item on your to-do list, it gets a lot easier.
2. “I don’t have enough money.”
This one feels real—especially when groceries, gas, and rent keep climbing.
But here’s the truth: saving isn’t about the amount. It’s about the habit.
Even if all you can spare is $5 a week, that small, consistent action builds momentum. It creates identity: I’m someone who saves. And that identity shift changes everything.
Waiting until you “have more” to begin saving is like waiting until you're fit to join a gym.
Start with what you have.
3. “I don’t know where to start.”
Nearly 1 in 4 Americans say they’re overwhelmed by the idea of creating a savings strategy. And we get it—the financial world can feel like alphabet soup: APY, CD, HSA, ETF...
This is where working with a financial educator can make a big difference.
You don’t have to figure it all out on your own. Just take the first step, and let someone experienced help you map out the rest.
Americans Are Feeling Financially Strained
Vanguard’s survey also highlights how emotionally loaded saving can be. In a climate of economic uncertainty, families are feeling vulnerable.
- 67% are unsure if they can stick to a savings plan this summer because of market volatility
- 63% expect to overspend on everyday needs like groceries or surprise expenses like home repairs
- 64% admit they don’t fully understand how interest rates affect their savings
That last one is especially important.
If you don’t understand how interest rates work, you might leave your money in places where it barely grows—or worse, loses value due to inflation.
But again, this isn’t a knowledge problem. It’s a confidence problem. And the antidote is financial education—the kind that leads to action.
Why Saving Without Strategy Isn’t Enough
Let’s say you’ve been putting away some money here and there. That’s great. But where you save matters too.
According to the Federal Deposit Insurance Corporation (FDIC), the average interest rate on a traditional savings account in May 2025 was just 0.42%.
That’s less than half a percent return on your money.
If you’re trying to build an emergency fund—or just earn a little interest while you save—that’s not going to cut it.
This is why financial literacy matters. You don’t need to be an expert, but you do need to know enough to make your money work for you—not sit idle.
A financial educator can help walk you through safe, smart options that offer better interest rates while still keeping your funds liquid and accessible.
The Cost of Doing Nothing
Let’s do some quick math.
Suppose you’ve been saving $10,000 in a traditional savings account earning 0.42%. That’s just $42 a year in interest.
Now imagine that same $10,000 earning 3.5%—a rate you can find in many insured accounts or cash alternatives.
That’s $350 a year, without doing anything extra.
It’s not just about saving—it’s about maximizing what you save.
When people say they feel like they’re falling behind financially, this is one of the reasons why. They’re putting money away, but it’s not growing. And without knowing it, they’re losing ground.
What Happens When You Actually Start?
Let’s flip the script.
What if instead of waiting for the perfect time to start saving, you decided to act today?
Even small steps create forward motion. That motion creates momentum. And that momentum leads to confidence and control.
We often say: action is the cure for anxiety. That’s true with saving too.
You don’t need to be perfect. You don’t need a financial windfall. You just need to begin.
And the best part? You don’t have to do it alone.
Meet with a Financial Educator
If you feel stuck or unsure, reach out to a financial educator. Not a salesperson. Not a pitch. A real, trained guide who can walk you through your options, show you how to take the first step, and help you build a plan that works for your life.
Working with a financial educator is like turning on your GPS. You still drive—but now you know where you’re going, and how to avoid the potholes along the way.
A Smart Saver’s Checklist
Here’s a simple, five-step plan to get started:
✅ Open a separate savings account (keep it out of sight, out of mind)
✅ Automate a deposit—start with $10/week if that’s all you can do
✅ Track your spending for one week to find hidden leaks
✅ Set a short-term savings goal, like $500 in three months
✅ Schedule a meeting with a financial educator to create a real plan
Remember: You don’t have to know everything. You just need to be willing to learn.
Final Word: The First Step Is the Most Important
You’re not behind. You’re not too late. And you’re not the only one who feels unsure.
But the difference between those who struggle financially and those who succeed often comes down to this:
They didn’t wait. They started.
If you’re ready to move from knowing to doing, we’re here for that. If you want help, meet with a financial educator today and get the support you need to take control of your savings, one decision at a time.
Start with one step. Let it snowball. Let your future self thank you.
Because when it comes to your money, clarity is power—and action is freedom.
Boomerang Kids
What Happens When “Later” Becomes “Now”
In 2025, it’s become more common than ever for young adults to return home.
They’re not teenagers. They’re not on summer break. These are grown children—some with degrees, jobs, or families of their own—moving back in with their parents.
According to Thrivent’s 2025 Boomerang Kids Survey, 46% of parents in the U.S. report that one or more of their adult children (ages 18–35) have moved back home. And for many families, this isn’t a temporary pause. It’s a new phase of life that’s forcing everyone to rethink what independence really means.
But while the reasons are wide-ranging, one root cause shows up again and again: a lack of financial readiness.
That’s where HowMoneyWorks for the Next Generation: Act Now or Pay Later comes in. Because the only way out of this cycle is to stop postponing financial education.
What’s Driving This Trend?
The data is clear.
Boomerang kids aren’t coming home because it’s convenient. They’re coming home because the cost of independence has skyrocketed.
According to the Thrivent survey:
- 32% of boomerang parents say the top reason their adult child returned home was unaffordable housing.
- The average federal student loan debt in 2024 was $37,853 per borrower, up from $27,759 a decade earlier.
- Wages have stagnated. For young men without a college degree, inflation-adjusted earnings are still lower than they were several years ago.
- Labor force participation among young men has declined over the long term.
- Divorce or separation is the second-leading cause of adults moving back in, cited by 1 in 5 parents.
These aren’t just statistics. They represent real challenges for young adults trying to launch into the world—and often falling short.
And while the reasons may be out of their control, the preparation doesn't have to be.
What It’s Costing Families
While the return home might create opportunities for reconnection, the financial toll is hard to ignore.
Thrivent reports:
- 38% of parents say the move has impacted their savings for long-term goals like retirement.
- 39% say it has disrupted their ability to save for short-term goals such as travel or home improvements.
- 55% of parents say they’ve had to reduce financial support in other areas.
The impact isn’t just on the young adults. It’s hitting the parents hard, too—especially those nearing retirement age. And as HowMoneyWorks for the Next Generation explains, waiting until "later" to prepare financially can come at a steep cost.
The Real Problem No One Taught Them to Solve
What do all these stats have in common?
They point to a generation that’s been under-equipped to handle financial life in the real world.
HowMoneyWorks for the Next Generation makes one thing painfully clear: most young people were never taught how money actually works. They didn’t learn how to build a budget, manage debt, understand insurance, or prepare for the unexpected. They were pushed toward degrees and jobs, but never given the roadmap to turn income into confidence for the future.
As a result, many of them learned the hard way—through debt, default, and delayed dreams.
That’s why the subtitle of the book isn’t just a slogan. It’s a warning: Act Now or Pay Later.
Because when financial literacy is postponed, the price is almost always paid later. In stress. In setbacks. In moving back home when you were supposed to be building your future.
The Path Forward Starts With Financial Literacy
The TheMoneyBooks series introduces readers to the 7 Money Milestones—a simple, proven framework for financial success. These aren’t buzzwords. They’re actionable steps:
- Financial Education
- Proper Protection
- Emergency Fund
- Debt Management
- Cash Flow
- Build Wealth
- Protect Wealth
These are the skills that transform boomerang kids into financially independent adults.
They help turn setbacks into launchpads. Confusion into confidence.
And for families currently living through this new normal, there is no better time to learn them than right now.
A Wake-Up Call, Not a Judgment
Let’s be honest—this isn’t easy.
No one dreams of moving back in with their parents. And no parent plans for their 30-year-old to be back under the same roof.
But this isn’t about shame or blame. It’s about opportunity.
If you’re in this season, it’s not too late to start building financial skills that last a lifetime. Whether you’re the parent or the young adult, this is your chance to take control—before life forces your hand again.
Don’t wait for perfect conditions. Start with what you have. Learn what you were never taught. And most importantly, begin the journey toward financial freedom—not just movement, but momentum.
Get Started Today
If your family is experiencing the boomerang effect, now is the time to learn together. HowMoneyWorks for the Next Generation is more than a book—it’s a financial wake-up call.
✅ Learn the 7 Money Milestones
✅ Discover how to avoid common traps like consumer debt and unprotected risk
✅ Understand why budgeting, saving, and investing are non-negotiables
✅ Take action today—so you’re not forced to pay the price tomorrow
Because independence isn’t just about moving out. It’s about moving forward.
Act Now. Teach Now. Plan Now.
Because waiting only makes the cost higher.
How to Avoid Graduating with $40,000 in Student Loan Debt

It’s official: the class of 2025 is stepping into college with the potential to graduate owing $40,000 in student loans. According to a recent NerdWallet analysis, nearly half of U.S. high school grads this year are heading to four-year colleges—and more than one-third of them are relying on student loans to get there. With federal student loan interest rates at a decade high, now more than ever, the question for students and families is: how can we avoid this debt trap?
Well the good news is there are smarter ways to navigate college costs. With a little planning, a better understanding of how money works, and some strategic choices, you can avoid starting your adult life deep in debt.
Why This Is a Big Deal
Student loans aren’t just numbers on a page. They follow you.
They can delay life goals like buying a car, renting an apartment, or saving for your future. And depending on the interest rate, you could end up paying back a lot more than you originally borrowed.
The problem is, most students don’t get a clear explanation of how borrowing really works. It’s no surprise—money basics like interest, budgeting, and debt aren’t often taught in school.
That’s why financial literacy matters now more than ever.
What Financial Literacy Can Do for You
When you understand how money works, everything changes. You start asking better questions. You compare options. You make decisions with your future in mind—not just the next semester.
Books like How Money Works For The Next Generation were created to fill in the gaps school doesn’t cover. It’s written with young people in mind and breaks down important concepts—like how compound interest works, how debt builds up over time, and why your early financial choices matter so much.
You don’t have to memorize everything or become a financial expert. But having a basic foundation can help you avoid some big, expensive mistakes.
10 Ways to Cut Down on Student Debt
Here are ten ways students and families can reduce (or even avoid) the need to borrow heavily for college:
1. Start at a Community College
Completing general education credits at a lower cost and transferring later can save thousands.
2. Pick a School That Fits Your Budget, Not Just Your Dream
It’s okay to be practical. Look at total cost, scholarship availability, and graduation rates before deciding.
3. Apply for FAFSA Early—Every Year
Federal aid, grants, and work-study opportunities start with this form. Don’t skip it.
4. Treat Scholarships Like a Part-Time Job
There are scholarships for everything from academics to community service to personal interests. Apply often.
5. Borrow Only What You Truly Need
Just because a loan is offered doesn’t mean you have to accept the full amount.
6. Get a Part-Time Job During School
A few hours a week can cover books, meals, or transportation—and reduce your need to borrow.
7. Live Simply While in School
This isn’t forever. Roommates, used books, and home-cooked meals can save you a lot now—and give you more freedom later.
8. Start Making Small Payments Now
Even while in school, making interest payments on your loans can prevent your balance from growing.
9. Understand How Interest Works
The more you know about how interest grows over time, the more cautious you’ll be with borrowing. Even simple concepts—like the Rule of 72—can change how you think about loans and credit.
10. Start Learning Now
The earlier you understand money, the more control you’ll have over it. Learning how to manage, budget, and build wealth doesn’t take a degree—it just takes a little time and curiosity.
You Don’t Need All the Answers Today—But You Do Need a Plan
No one expects you to figure out your entire financial life before you finish high school. But starting with the basics now can make a huge difference later.
Whether it’s talking to a financial professional, reading a book, watching videos, or asking questions—what matters is that you take that first step. Not because someone told you to, but because your future is worth it.
Financial literacy won’t just help you get through college. It’ll help you get ahead—on your own terms.
Want to learn more about student loans, saving strategies, and how to make money work for you instead of against you?
Books like How Money Works For The Next Generation are a good place to start. They won’t tell you what to do—they’ll help you understand your options.
Because once you know how money works, you can Stop Being a Sucker® and get to call the shots.